
While the S&P 500 is up 21.4% since March 2026, Arthur J. Gallagher (currently trading at $227.70 per share) has lagged behind, posting a return of 5.4%. This might have investors contemplating their next move.
Taking into account the weaker price action, is now a good time to buy AJG, or is it a pass? Find out in our full research report, it’s free.
Why Is Arthur J. Gallagher a Good Business?
Founded in 1927 and operating in approximately 130 countries through direct operations and correspondent networks, Arthur J. Gallagher (NYSE:AJG) provides insurance brokerage, reinsurance, consulting, and third-party claims settlement services to businesses and individuals worldwide.
1. Skyrocketing Revenue Shows Strong Momentum
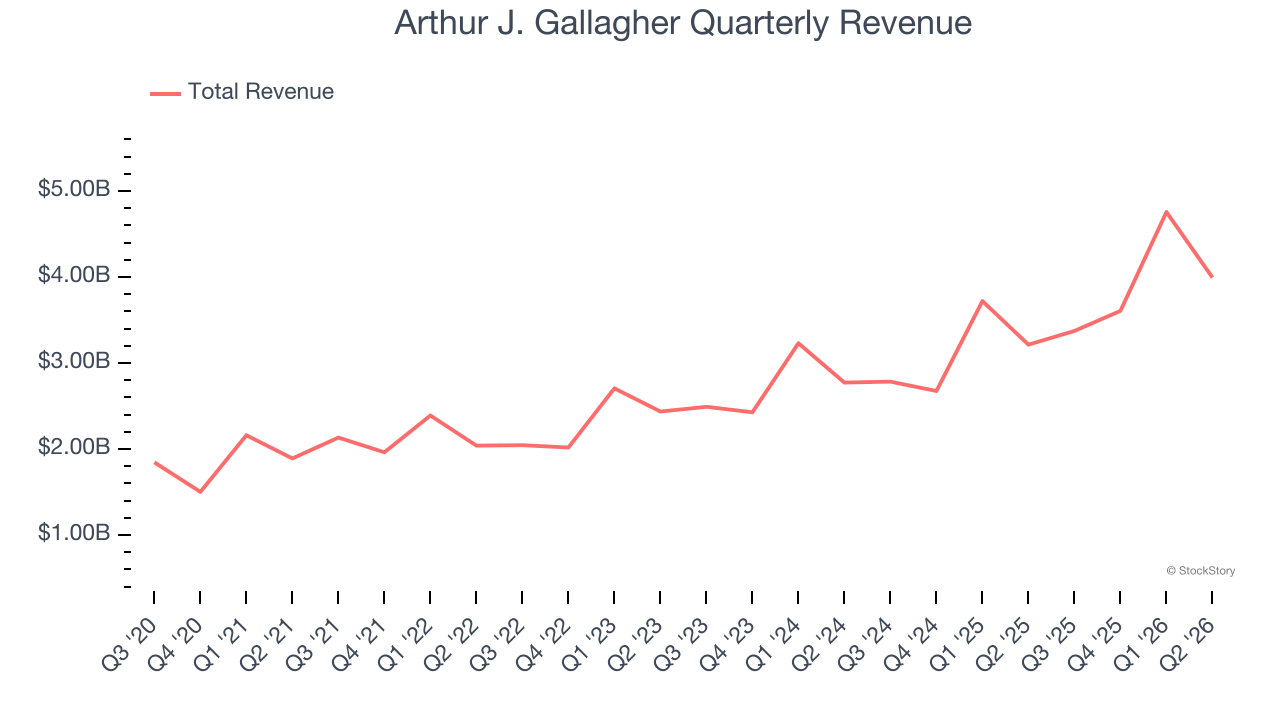
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Thankfully, Arthur J. Gallagher’s 16.3% annualized revenue growth over the last five years was incredible. Its growth beat the average business services company and shows its offerings resonate with customers.
2. Outstanding Long-Term EPS Growth
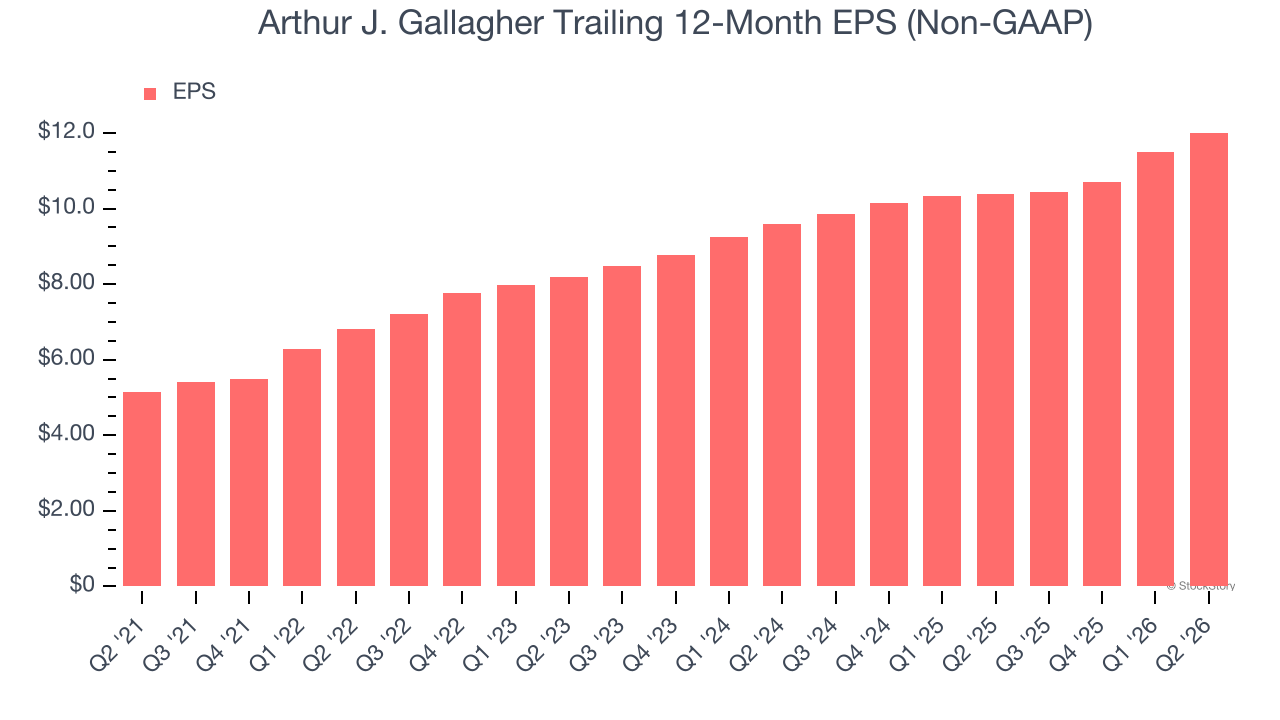
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Arthur J. Gallagher’s EPS grew at 18.5% compounded annual growth rate over the last five years, higher than its 16.3% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
3. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
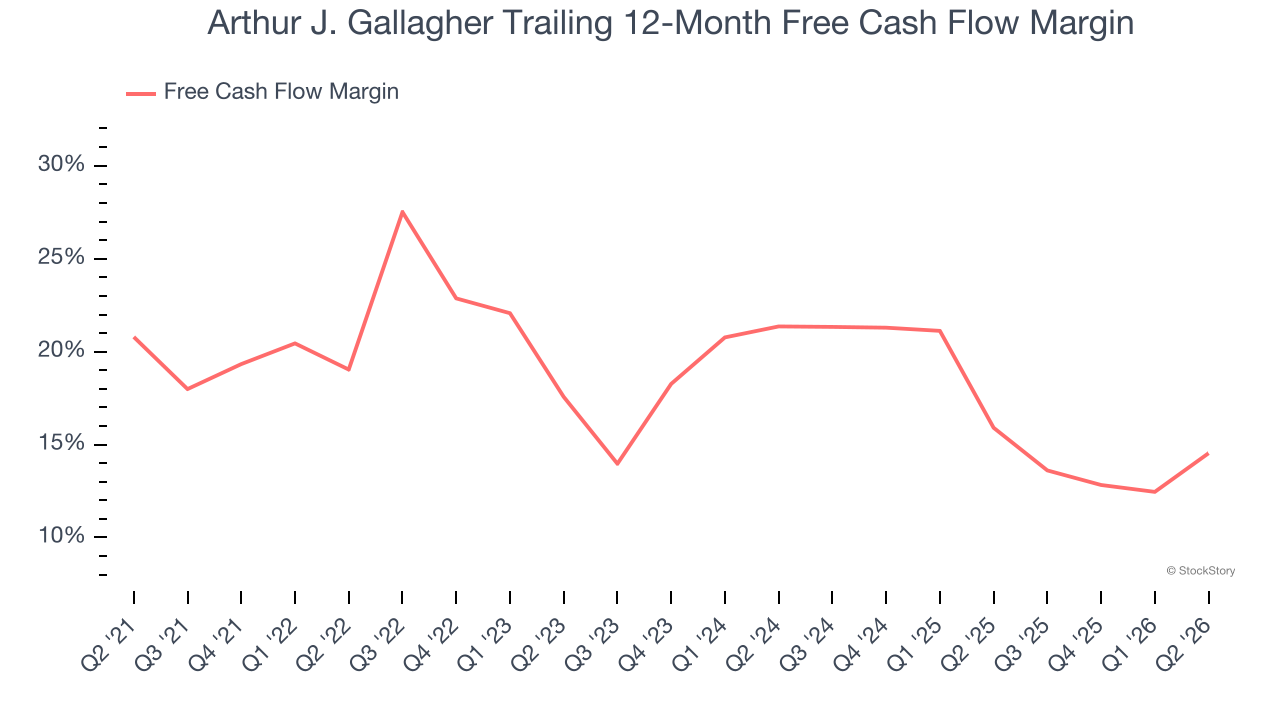
Arthur J. Gallagher has shown terrific cash profitability, enabling it to reinvest, return capital to investors, and stay ahead of the competition while maintaining an ample cushion. The company’s free cash flow margin was among the best in the business services sector, averaging 17.3% over the last five years.
Final Judgment
These are just a few reasons why we think Arthur J. Gallagher is an elite business services company. With its shares underperforming the market lately, the stock trades at 16.2× forward P/E (or $227.70 per share). Is now a good time to initiate a position? See for yourself in our comprehensive research report, it’s free.
Stocks We Like Even More Than Arthur J. Gallagher
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.